Can Long-Term Care Insurance Pay a Family Member as a Caregiver?
Yes, with some policies, including the coverage Staying Power offers. Because it pays a cash benefit, you can use it to pay a family member or friend for care, as long as a U.S.-licensed health care practitioner’s plan of care states that informal care is appropriate. Not every long-term care policy allows this.
How does paying a family member work?
It comes down to how a policy pays benefits. Reimbursement policies pay for qualifying services, often from licensed providers, after you submit bills. Cash indemnity policies, including the coverage we offer, pay your monthly benefit directly to the policyowner once a claim is approved, and you decide how to use it.
That flexibility is what makes it possible to pay a daughter, son, sibling, friend, or other trusted person to provide care.
The NAIC’s consumer guide notes that most policies do not pay benefits to family members who provide care, so it’s important to check the policy terms. (NAIC Shopper’s Guide)
What’s required?
With the coverage we offer, informal care from family or friends is allowed when the plan of care, prepared by a U.S.-licensed health care practitioner at the time of your claim, states that it’s appropriate. The claim is recertified at least every 12 months.
The caregiver doesn’t need to be licensed, as long as the plan of care supports informal care.
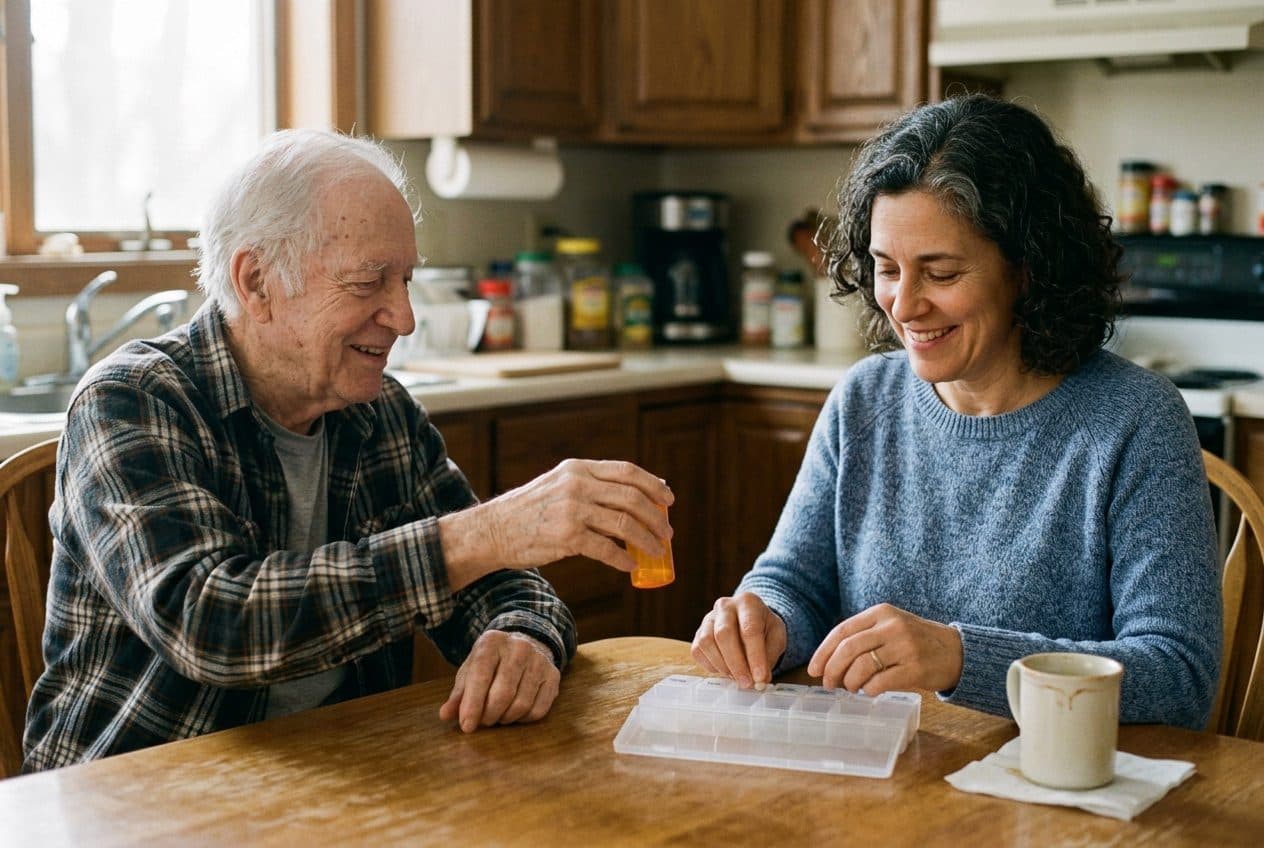
Why would you want to pay a family member?
Care comes from someone you already know and trust
A family member who cuts back on work to help can be paid for that time
Informal care can cost less than agency care, which may stretch your benefit further
What should families talk about first?
Paying a family member works best when roles are agreed on in advance, who provides care, for how many hours, and what happens if that person can’t continue. It’s worth having that conversation early, while it’s still hypothetical.
Payments to a family caregiver may have tax implications for them. A tax advisor can help.
Staying Power is a licensed insurance agency that helps families plan who provides care and how it’s paid for.
To see what coverage could look like for your family, start with a few questions. For more on how benefits work, see How Does Long-Term Care Insurance Work?.
Related reading: How to Divide Caregiving Between Siblings and What Happens When You File a Long-Term Care Insurance Claim?.
Frequently asked questions
Does the family caregiver need a license?
With the coverage we offer, no: as long as the plan of care states that informal care is appropriate.
Can I use benefits for both professional and family care?
Yes. With a cash indemnity benefit, you can combine types of care in whatever way works for you.
Do all long-term care policies allow this?
No. Reimbursement-based policies may limit payment to licensed providers. Check the policy terms before you buy.