Start your plan
AboutBlogStart your plan
Start your plan

Library / Living Well at Home

Questions to Ask Before Hiring In-Home Care
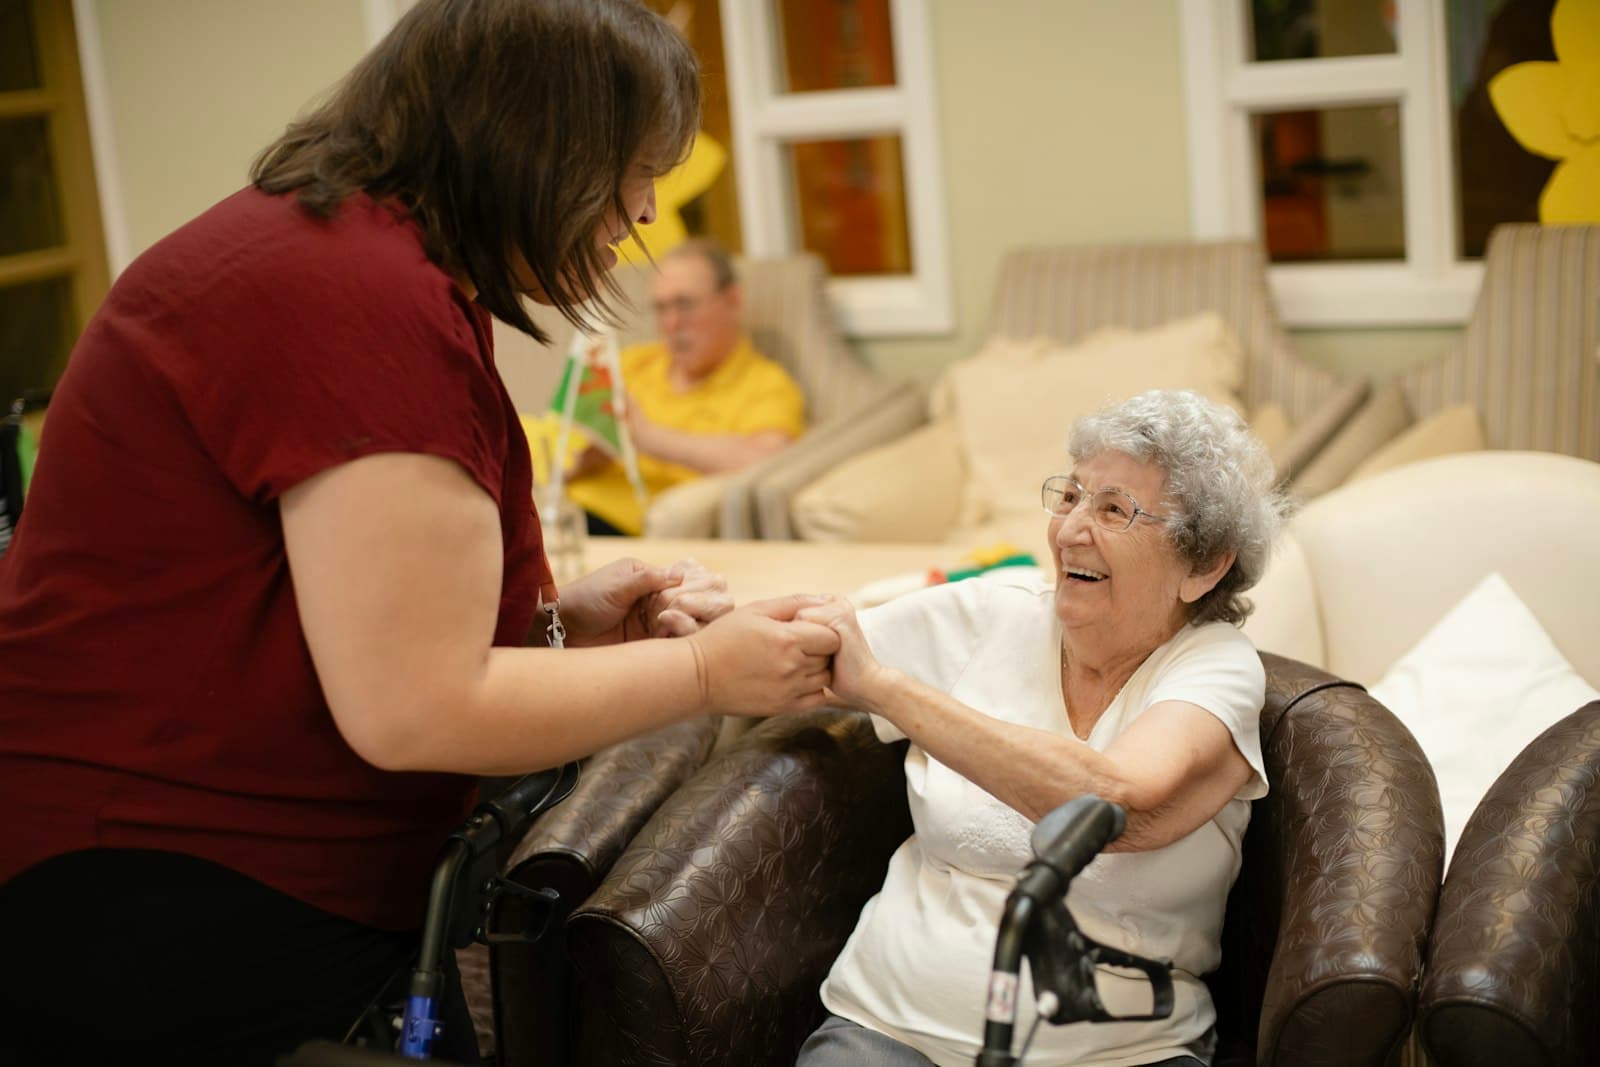
A home caregiver helping an older woman with her walker in her living room

By Stephanie Cheney, Founder & CEO, Licensed Insurance Agent | Last reviewed: October 10, 2026

Before hiring in-home care, ask whether caregivers are agency employees, how they’re screened and trained, whether the agency is licensed, bonded, and insured, how missed shifts are covered, and exactly what services and rates are included. If you hire someone directly, you take on responsibilities an agency would otherwise handle.

Start your plan

Agency or independent caregiver?

Agencies handle screening, payroll, backup coverage, and insurance, usually at a higher rate. Hiring directly can cost less, but you may become a household employer, with tax and insurance responsibilities. See IRS Publication 926 and talk with a tax advisor.

What should you ask the agency?

  • Are you licensed in this state?

  • Are you bonded and insured?

  • Are caregivers employees or contractors?

  • How are caregivers screened and trained?

  • Who supervises them?

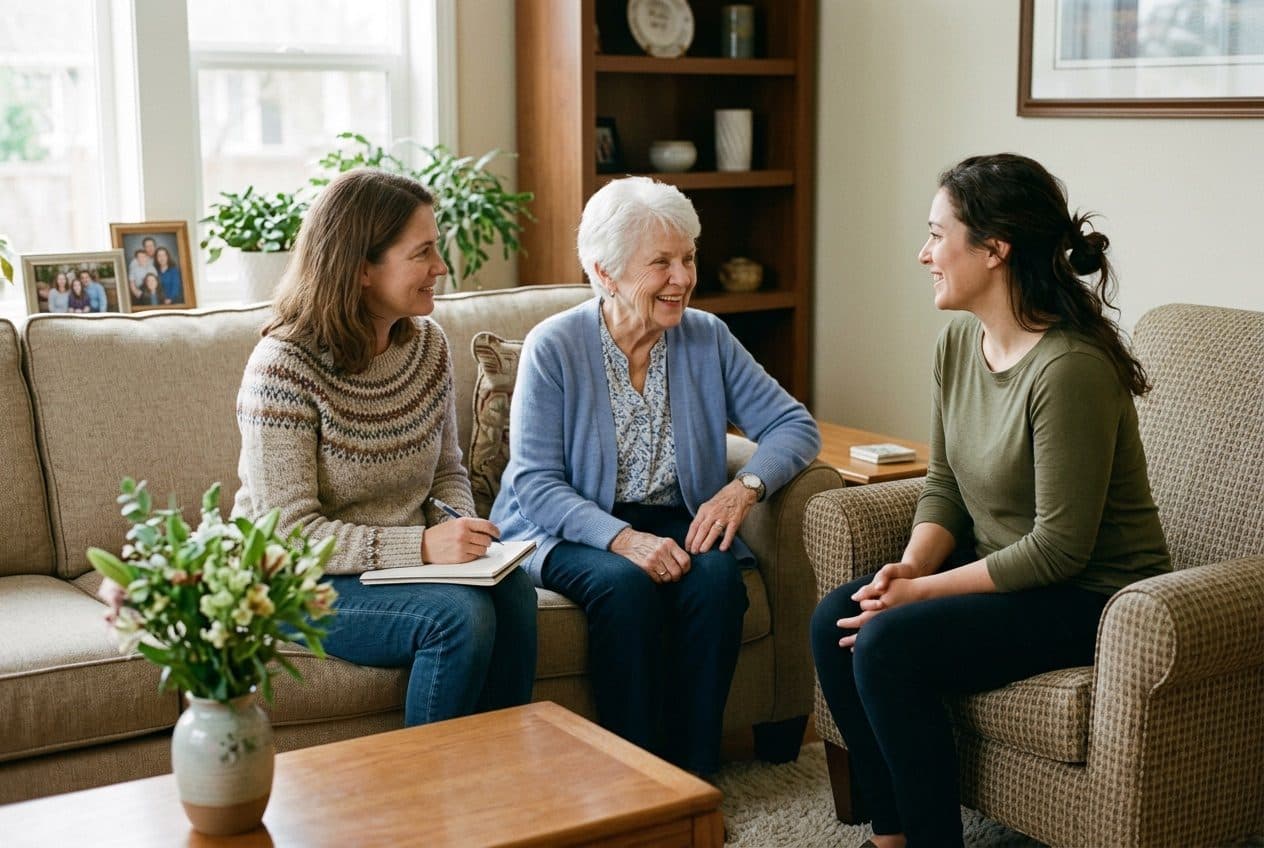
A daughter and her mother interviewing a home aide in the living room

What should you ask about caregivers?

  • Will we have the same caregiver most of the time?

  • How do you match caregivers to clients?

  • What happens if a caregiver is sick or doesn’t show up?

What should you ask about services and cost?

  • What’s the hourly rate, and is there a minimum number of hours?

  • What’s included: companionship, personal care, medication reminders?

  • How does billing work, and what are the contract terms?
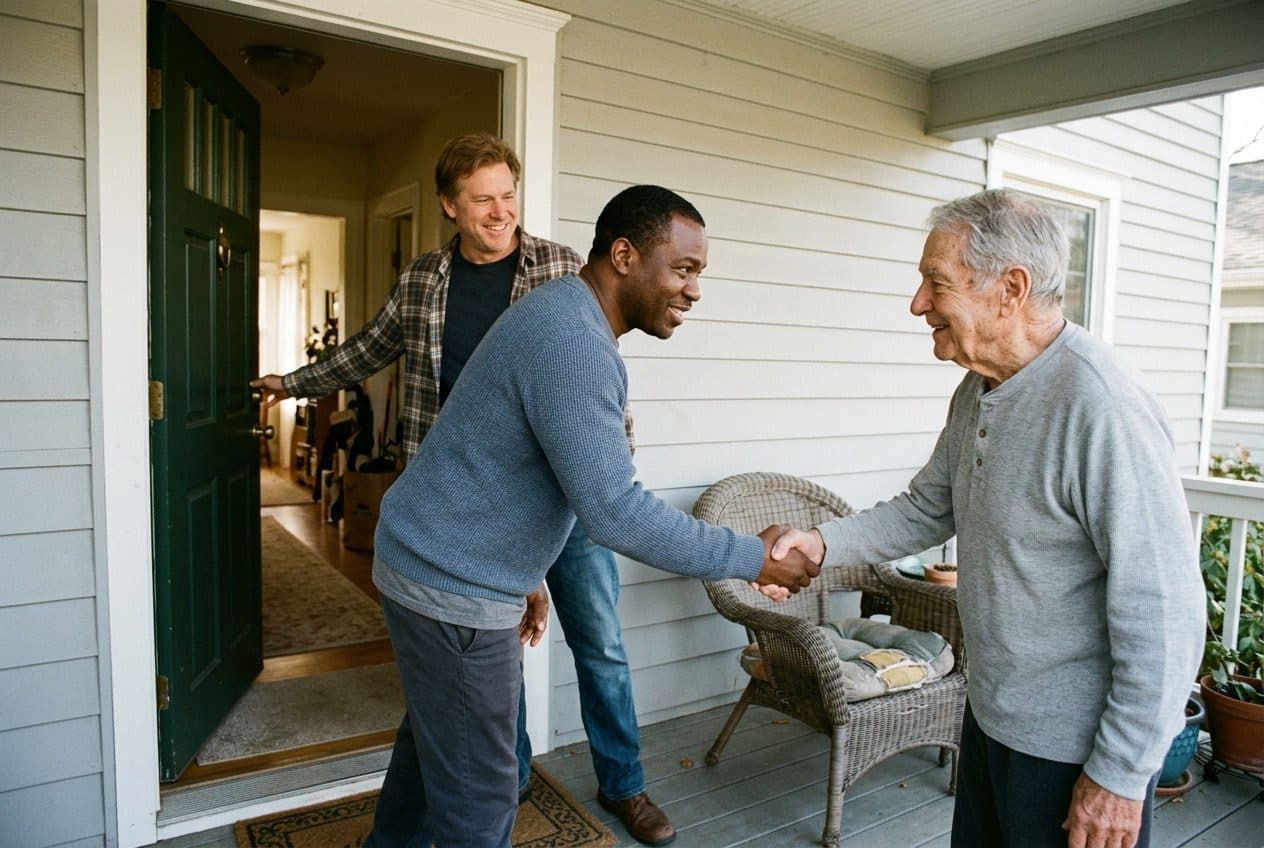
A father and son welcoming a home aide at their front door

What are the red flags?

  • Vague answers about screening or insurance

  • Pressure to sign a long contract quickly

  • No clear plan for missed shifts

How do people pay for in-home care?

Staying Power is a licensed insurance agency that helps people plan how in-home care would be paid for.

At national median rates, a home care aide costs about $35 an hour. (CareScout) Medicare doesn’t cover ongoing custodial care. With the coverage we offer, long-term care insurance pays a cash benefit you can use for an agency or an independent caregiver. Reimbursement-based policies may limit which providers they pay. Get started to see what care costs and how to fund it.

Related reading: How Much Help at Home Do You Actually Need?, How Much Does Long-Term Care Cost?, and Signs a Parent Needs More Help at Home.

Frequently asked questions

Does Medicare pay for in-home care?

Medicare may cover part-time skilled home health care if you’re homebound. It doesn’t cover ongoing custodial care.

Is an agency or a private caregiver better?

Agencies offer more protection and backup; private caregivers can cost less but add employer responsibilities.
Get more details about long-term care insurance

Sources

  • CareScout: 2025 Cost of Care Survey

  • IRS: Publication 926, Household Employer’s Tax Guide

About the author

Stephanie Cheney is the founder and CEO of Staying Power and a licensed insurance agent (OK License #3004465615 · TX License #3562695). She became a caregiver at 20 and saw firsthand what caregiving asks of a family: time, career, and money. After her father died, her mother bought long-term care insurance in her 50s. When brain surgery in her 60s left her mother needing full-time care, that coverage meant Stephanie could keep working and hire help when she was away. Her mother has lived with her for about 10 years. Stephanie started Staying Power to help people plan to stay in their own homes as they age, beginning with how they'll pay for care.

About the cost figures

Cost figures are national medians from CareScout's 2025 Cost of Care Survey and are not projections. Actual costs vary by location, provider, and level of care.

About the coverage described

Features described reflect the coverage Staying Power offers, issued by Nationwide Life and Annuity Insurance Company through the CareMatters product line. Guarantees are backed by the claims-paying ability of the issuing insurer. Benefits may be reduced by loans, withdrawals, or unpaid charges. Features vary by product and state; coverage is governed by the terms of the issued policy.

Disclosure

Staying Power is a licensed insurance agency. This article is intended to solicit insurance business and is provided for educational purposes only. It is not tax, legal, medical, or financial advice, and it is not a recommendation to purchase, an offer of coverage, or a quote. Long-term care insurance is subject to medical underwriting and is not available to everyone. Benefits, limitations, and exclusions vary by policy, carrier, and state. Medicare and Medicaid rules vary by state and change over time; see Medicare.gov and your state Medicaid agency for current details.

More in Living Well at Home

  • Making Your Home Age-Ready, Room by Room

    A room-by-room guide to making your home safer and easier to live in as you age, from the bathroom to the front door.

  • Staying Connected as You Age

    Why social connection matters as you age, and practical ways to stay involved, find purpose, and get around when driving gets harder.

  • How Much Help at Home Do You Actually Need?

    The range of help at home, from a few hours a week to around the clock, what each level looks like, and what it costs.

Explore

AboutQuestions2026 Planning Report

Get started

Start your insurance plan

Contact

301 E Archer St, Tulsa, OK 74120

info@stayingpower.co

Staying Power is a licensed insurance agency. Insurance products are offered through licensed insurance agents and are issued and underwritten by third-party insurance companies. Products, features, and availability vary by state and are subject to underwriting approval. Individual care needs and expenses vary; no policy is guaranteed to cover the entire cost of care. Policy guarantees are backed by the claims-paying ability of the issuing insurer. Any values shown in interactive tools are illustrative only and do not constitute a quote, offer, or guarantee of coverage or benefits. This site provides general information and is not financial, legal, or tax advice.

Staying Power is not affiliated with or endorsed by any government agency. State license information is available on our license information page.

This website is intended to solicit insurance business.

Privacy noticeTerms and conditionsLicense information

© 2026 Staying Power