Start your plan
AboutBlogStart your plan
Start your plan

Library / Caring for a Parent

The First 30 Days After a Parent’s Fall or Hospital Stay
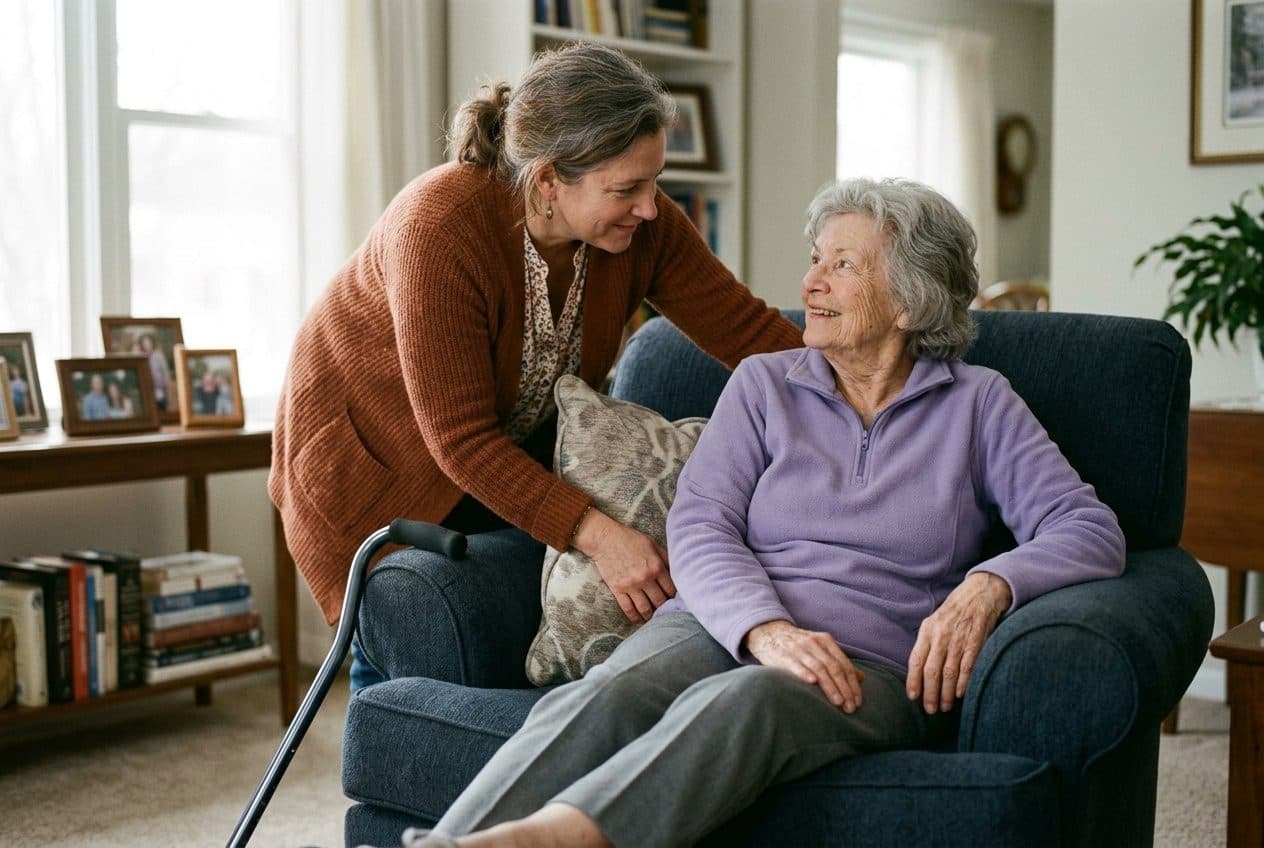
An adult daughter helping her mother settle into an armchair at home

By Stephanie Cheney, Founder & CEO, Licensed Insurance Agent | Last reviewed: October 10, 2026

In the first 30 days, focus on a safe discharge plan, understanding what Medicare will and won’t cover, arranging help at home or rehab, and making the home safer to prevent another fall. Ask early whether your parent has been formally admitted as an inpatient, because that affects Medicare coverage for rehab.

Start your plan

What should you ask before discharge?

  • Ask to speak with the hospital’s discharge planner.

  • Ask whether your parent is an inpatient or under observation. Medicare requires a qualifying inpatient stay of at least three days to cover skilled nursing facility care, and time under observation doesn’t count toward it.

  • Ask what care is needed after discharge, which medications have changed, and what equipment is required.

What does Medicare cover next?

If your parent qualifies, Medicare covers up to 100 days of skilled nursing facility care per benefit period, with a daily coinsurance after day 20, and only while daily skilled care is needed. (Medicare.gov) Medicare may also cover part-time skilled home health care if your parent is homebound. It doesn’t cover ongoing custodial care. See Does Medicare Cover Long-Term Care?.

What happens in the first weeks home?

  • Week 1: confirm medications, follow-up appointments, and equipment.

  • Weeks 2–4: make safety changes, arrange help, and watch for new signs of trouble.

See Making Your Home Age-Ready, Room by Room and Signs a Parent Needs More Help at Home.
A woman using a wheelchair slices peppers in her own kitchen

What happens when skilled care ends?

This is where many families hit a gap. If your parent still needs help with daily activities, someone has to provide it and someone has to pay for it. Home care runs about $35 an hour at national median rates. (CareScout) Options include savings, family, and Medicaid if eligible; see Long-Term Care Insurance vs. Medicaid.

How do you take care of yourself?

Staying Power is a licensed insurance agency that helps people plan how care would be paid for before they need it.

See How to Care for a Parent Without Losing Your Career. And when things settle, think about your own plan. Get started to see what care costs and how to fund it.

Frequently asked questions

What is observation status?

It means your parent is being treated as an outpatient, even if they stay overnight. Observation time doesn’t count toward the three-day inpatient stay Medicare requires for skilled nursing facility coverage.

How long will Medicare pay for rehab?

Up to 100 days of skilled nursing facility care per benefit period, after a qualifying hospital stay, and only while daily skilled care is needed.

Who pays for help after Medicare stops?

Usually savings, family, Medicaid if eligible, or long-term care insurance if your parent has it.
Get more details about long-term care insurance

Sources

  • Medicare.gov: Skilled Nursing Facility Care

  • CareScout: 2025 Cost of Care Survey

About the author

Stephanie Cheney is the founder and CEO of Staying Power and a licensed insurance agent (OK License #3004465615 · TX License #3562695). She became a caregiver at 20 and saw firsthand what caregiving asks of a family: time, career, and money. After her father died, her mother bought long-term care insurance in her 50s. When brain surgery in her 60s left her mother needing full-time care, that coverage meant Stephanie could keep working and hire help when she was away. Her mother has lived with her for about 10 years. Stephanie started Staying Power to help people plan to stay in their own homes as they age, beginning with how they'll pay for care.

About the cost figures

Cost figures are national medians from CareScout's 2025 Cost of Care Survey and are not projections. Actual costs vary by location, provider, and level of care.

Disclosure

Staying Power is a licensed insurance agency. This article is intended to solicit insurance business and is provided for educational purposes only. It is not tax, legal, medical, or financial advice, and it is not a recommendation to purchase, an offer of coverage, or a quote. Long-term care insurance is subject to medical underwriting and is not available to everyone. Benefits, limitations, and exclusions vary by policy, carrier, and state. Medicare and Medicaid rules vary by state and change over time; see Medicare.gov and your state Medicaid agency for current details.

More in Caring for a Parent

  • How to Care for a Parent Without Losing Your Career

    How to balance caregiving and a career: talking to your employer, using FMLA, sharing the load, and paying for outside help.

  • Signs a Parent Needs More Help at Home

    The signs that an aging parent may need more help at home, what to do when you notice them, and where to find support.

  • How to Divide Caregiving Between Siblings

    How siblings can share caring for an aging parent: holding a family meeting, dividing tasks by strengths, and handling disagreements.

Explore

AboutQuestions2026 Planning Report

Get started

Start your insurance plan

Contact

301 E Archer St, Tulsa, OK 74120

info@stayingpower.co

Staying Power is a licensed insurance agency. Insurance products are offered through licensed insurance agents and are issued and underwritten by third-party insurance companies. Products, features, and availability vary by state and are subject to underwriting approval. Individual care needs and expenses vary; no policy is guaranteed to cover the entire cost of care. Policy guarantees are backed by the claims-paying ability of the issuing insurer. Any values shown in interactive tools are illustrative only and do not constitute a quote, offer, or guarantee of coverage or benefits. This site provides general information and is not financial, legal, or tax advice.

Staying Power is not affiliated with or endorsed by any government agency. State license information is available on our license information page.

This website is intended to solicit insurance business.

Privacy noticeTerms and conditionsLicense information

© 2026 Staying Power